Your regular vet’s office is small, well-equipped for everyday problems, and staffed by people who genuinely know your pet. What it probably isn’t is a 24-hour trauma center with an ICU, a blood bank, and specialists on call. So when something goes seriously wrong — your dog collapses, your cat stops breathing normally, there’s internal bleeding suspected, or a condition needs surgery your vet’s clinic simply isn’t set up to perform — the plan shifts fast. Your vet stabilizes what they can and then says some version of: “You need to get them to the emergency hospital right now.”
That handoff is called a referral or transfer, and it happens constantly in veterinary medicine. General practice vets are trained to recognize when a case is beyond their equipment or expertise, and part of good care is knowing when to say so. Common transfer scenarios include toxin ingestion requiring intensive monitoring, bloat or GDV in dogs, severe trauma from being hit by a car, breathing difficulties, seizures that won’t stop, or a surgical emergency after hours when your regular clinic is closed. In cities, that specialty or 24-hour hospital might be fifteen minutes away. In rural areas, it can be an hour or more.
Here’s the part that catches people off guard: someone has to physically get the animal there, and it isn’t always as simple as tossing them in your back seat. A pet in critical condition may need to be kept flat, monitored, on oxygen, or receiving fluids during the drive. That’s where animal ambulance and transfer services come in — and where a whole new, often unexpected cost shows up in the middle of an already frightening day.
How ground animal ambulance services work and typical price ranges by region
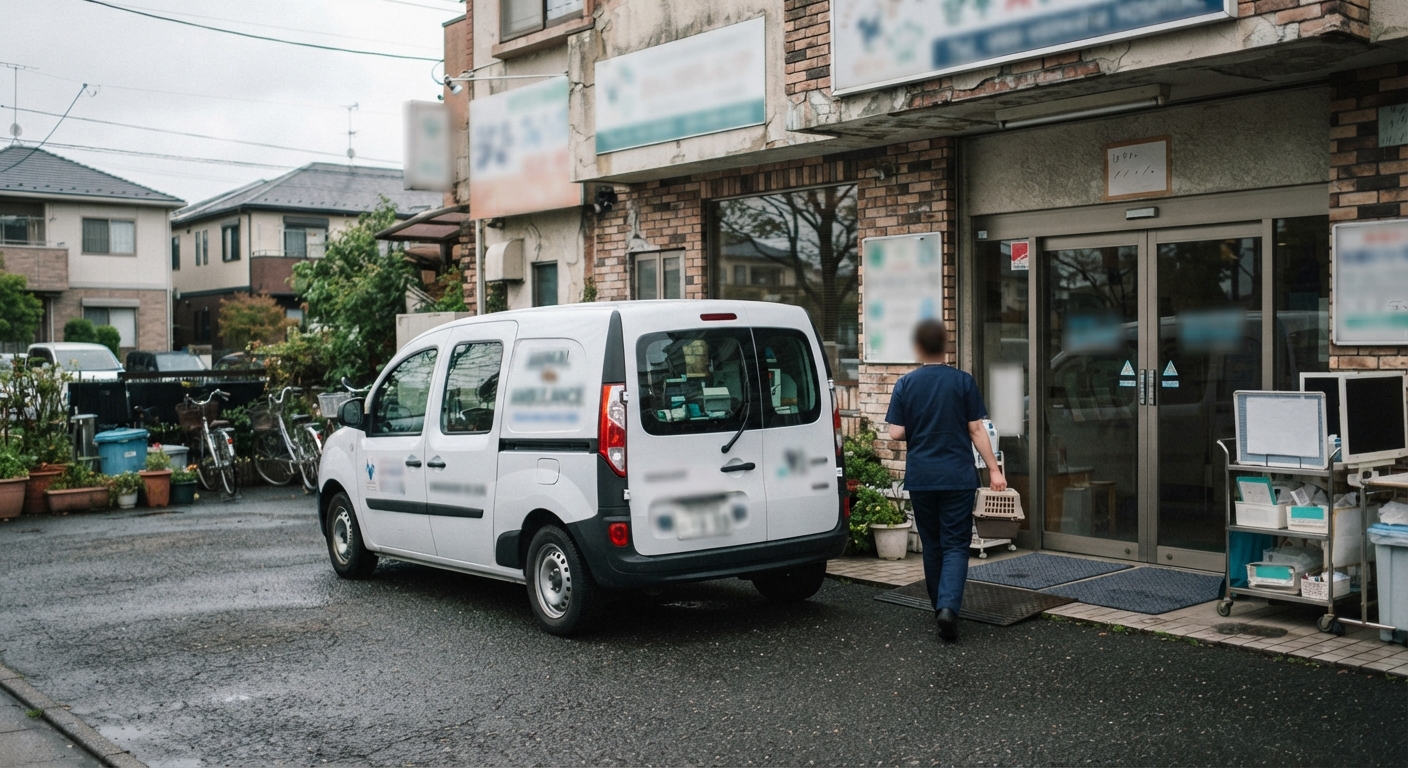
Animal ambulances work a lot like the human version, scaled down. A vehicle — sometimes a converted van, sometimes something closer to a shuttle — is outfitted with a stretcher or crate restraint system, oxygen supply, and in some cases a technician trained to monitor vitals during transport. Some services are run independently and dispatch on request. Others are affiliated with a specific emergency hospital and used mainly to move patients between that hospital and referring clinics, or to pick up patients from a home when the owner can’t safely transport them.
Availability varies enormously by where you live. Large metro areas with a robust network of specialty and emergency hospitals are more likely to have a dedicated pet ambulance service, sometimes even more than one competing for the business. Smaller cities and rural areas may have none at all, which means the “transfer” is really just you, your car, and hopefully a calm enough animal to make the drive without a professional in the back seat managing their condition.
Pricing tends to follow a base fee plus mileage structure, similar to how a human ambulance bills, though the numbers are generally lower. A short in-town transfer will cost less than a longer haul to a hospital across a metro region or into a neighboring county. Add-ons matter too — a transport with a technician monitoring oxygen and vitals the entire way will cost more than a basic transfer where the animal is simply secured and driven. Time of day and urgency also factor in; a scheduled daytime transfer is typically cheaper than an urgent nighttime dispatch. Because there’s no standardized national rate and few markets have more than one or two providers, prices can swing widely between regions, and you may find the fee is simply whatever the sole local provider decides to charge.
The practical takeaway is that this is a real line item, not a rounding error, and it shows up on top of whatever the receiving hospital charges for the emergency visit itself. If your vet says “we’re calling for a transport,” it’s worth asking upfront what the estimated cost will be before the vehicle is dispatched, if the situation allows even a minute for that question.
Rare but real air transport situations and their steep costs
Air transport for pets is uncommon, but it does happen, mostly in two situations: a pet needs a highly specialized procedure only available at a distant referral center, or ground transport simply isn’t feasible in the time window that matters — think a rural area with the nearest capable hospital hours away by car. Some organizations that handle animal rescue and relocation also offer emergency flight coordination, and a small number of private charter services will take on medical transport cases for animals when arrangements are made in advance.
The cost here is in an entirely different category than ground transport. Chartering any aircraft is expensive by nature, and adding medical equipment, a handler, or a technician on board raises that further. This is not something most pet owners will ever need, and it’s also not something most people can reasonably budget for as a routine possibility. If you live somewhere genuinely remote, with the nearest emergency or specialty hospital a long drive away, it’s worth knowing this option exists at least in theory — but treat it as a break-the-glass scenario, not a line item in your everyday emergency planning.
Why most pet insurance policies exclude transport and transfer fees as ‘non-medical’
If you have pet insurance, you might assume that getting your pet to the hospital that can actually save them would be covered — after all, it’s clearly part of the emergency. Most policies see it differently. Pet insurance is generally built to reimburse for the diagnosis and treatment of a covered condition: exams, diagnostics, medications, surgery, hospitalization. The ambulance ride or interclinic transfer that got your pet to the place where that treatment happened is typically classified as a transport or logistics cost, not a medical treatment cost, and many policies exclude it outright or simply never mention it because it falls outside what they define as eligible expenses in the first place.
This isn’t unique to pet insurance — human health insurance has a long history of similar gaps around ambulance billing, which is part of why “surprise ambulance bill” is such a familiar phrase for people navigating their own medical care. The logic insurers apply is that the treatment is the insurable event; how the patient physically arrived is treated as incidental, even when in practice it wasn’t optional at all.
There’s also a practical administrative reason this gap exists: transport is often provided by a third party that isn’t the treating veterinary hospital, billed separately, and sometimes paid in cash or by card on the spot before the animal is even accepted at the receiving facility. That kind of fragmented billing doesn’t fit neatly into a claim built around itemized veterinary invoices, so insurers tend to draw the line at the hospital door.
Some policies do specify limited exceptions or add-on riders for transport, and coverage details change over time, so this is genuinely worth checking in your own policy documents or by asking your provider directly rather than assuming either way. But as a general pattern, don’t count on your pet insurance to soften this particular cost. Plan as if it’s coming entirely out of your own pocket, and treat any actual coverage you find as a pleasant surprise rather than a given.
Questions to ask your vet or ER about transfer logistics before you’re in crisis mode
The best time to understand how transfers work in your area is not while you’re standing in an exam room watching your pet get loaded into a van. A calm conversation ahead of time, even a quick one during a routine annual visit, can save you a lot of scrambling later. Consider asking your regular vet:
Which specialty or 24-hour emergency hospital do you typically refer to, and how far away is it from where I live? Do you have a working relationship with a ground ambulance or transport service, and do you know roughly what they charge? If a transfer happens after your clinic’s normal hours, who actually arranges it — your staff, the receiving hospital, or me? And is there any situation where transport by a family member, rather than a professional service, would actually be unsafe for my pet, versus just less comfortable?
It’s also worth calling your nearest emergency or specialty hospital directly, even when nothing is wrong, just to ask how they typically handle incoming transfers and whether they can point you to transport options they trust. Front desk staff at these hospitals field this kind of question often enough that it won’t seem strange, and having even one phone number saved in your contacts before you need it can shave real minutes off a response time later.
Building transport costs into your emergency fund and knowing which nearby hospitals can actually treat serious cases
Most advice about pet emergency funds focuses on the treatment itself — surgery, hospitalization, diagnostics. That’s the right priority, but it’s worth setting aside a mental (or literal) line item for getting there in the first place, especially if you live somewhere without a nearby 24-hour hospital or where you already know ground transport would likely be needed for anything serious. Even a modest cushion earmarked for “getting to the hospital” means you’re not making a financial decision under pressure about whether to call a transport service or attempt the drive yourself with a pet who may not be stable enough for it.
Beyond the money, the more valuable prep work is simply knowing your local landscape before you need it. Not every animal hospital that calls itself an emergency clinic is equipped to handle every kind of critical case — some have surgeons on site around the clock, others stabilize and then refer onward themselves, which can mean a second transfer on top of the first. Knowing in advance which hospital in your area is the real endpoint for serious cases, rather than just the closest one, can spare you from a transport that gets your pet to a building that then has to send them somewhere else anyway.
None of this is pleasant to think about, which is exactly why so few people do it until they’re in the middle of it. But a few minutes of research now — a saved phone number, a rough sense of local pricing, a clear read on what your policy will and won’t cover — turns a moment of crisis into one where you at least know what’s coming next, even if you can’t control everything about the bill.