What genetic health screening panels test for and how they differ from basic breed ID kits
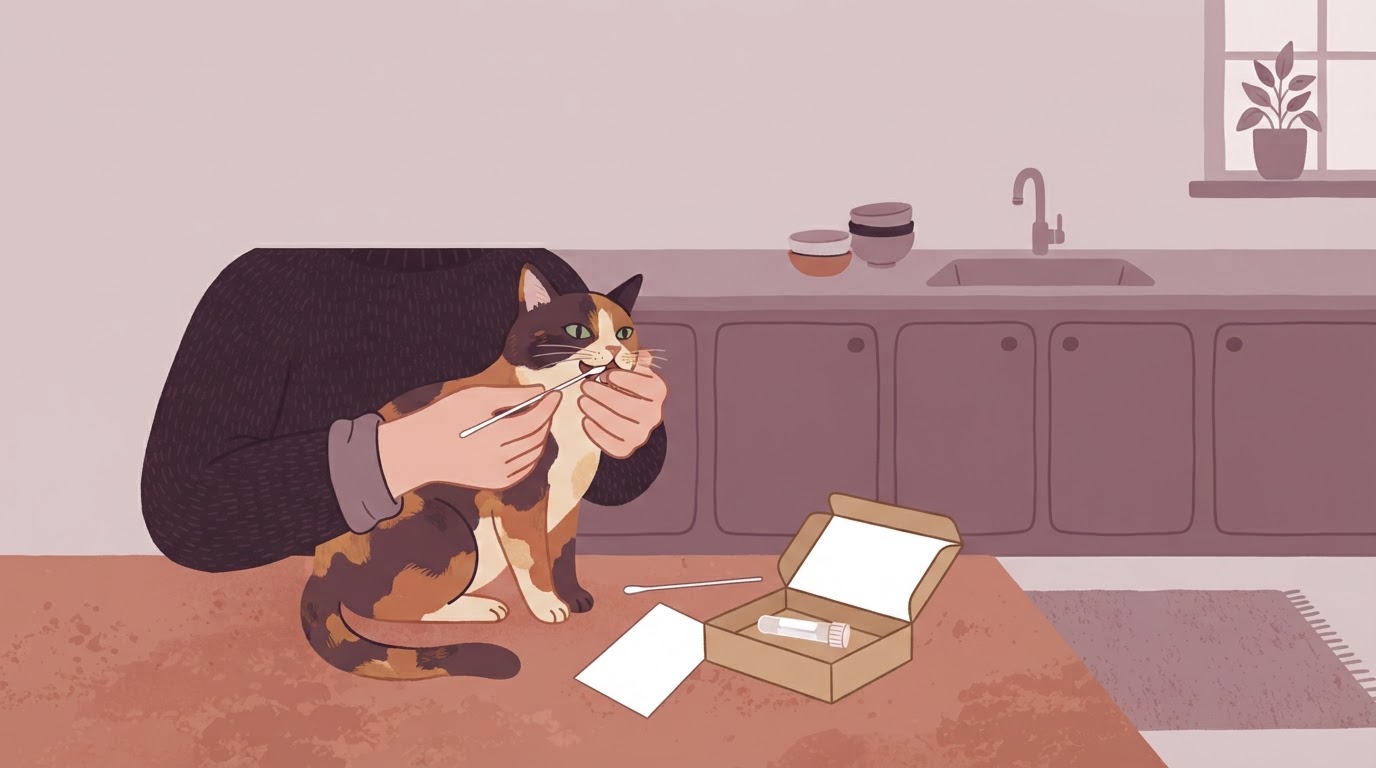
If you’ve spent any time near a pet store checkout or scrolled past an ad for a cheek-swab kit, you’ve probably seen two different products marketed side by side: breed identification kits and genetic health screening panels. They sound similar, and they use the same basic swab-and-mail process, but they’re answering very different questions.
A breed ID kit is mostly a curiosity product. It compares your dog’s or cat’s DNA against a reference database and tells you what breeds or ancestral groups show up, sometimes with a rough percentage breakdown. It’s fun for mixed-breed dogs and cats especially, but on its own it doesn’t tell you much about health risk beyond “this breed group is statistically more prone to X,” which is a very loose kind of information.
A genetic health screening panel goes further. Instead of just estimating ancestry, it looks for specific gene variants known to be associated with particular inherited conditions — things like certain heart conditions, kidney diseases, bleeding disorders, vision problems, or drug sensitivities that show up more often in some breeds and lines than others. Some panels also screen for carrier status, meaning your pet might not develop a condition themselves but could pass a gene along if they were ever bred, which matters less to the average pet owner but is included anyway because the same lab tech runs the same panel for everyone.
The more comprehensive panels test for dozens to a few hundred markers. Some are broad multi-breed panels designed to cover a wide range of possible conditions regardless of what breed mix shows up. Others are more targeted, built around markers that are well-documented in certain breeds. None of them test for every possible health condition, and none of them can tell you whether your pet will actually develop a disease — only whether they carry a genetic marker that’s been associated with increased risk in study populations.
Typical price ranges for at-home kits versus vet-administered panels
Cost is one of the more confusing parts of this whole category, because the price tag doesn’t always match up neatly with how much information you get.
At-home kits you order online and swab yourself tend to sit at the lower end, and combine breed ID with a health panel as a bundle. These are convenient and don’t require a vet visit, but the tradeoff is that you’re the one interpreting the report, often with a customer-facing summary rather than a full clinical breakdown, and there’s no vet in the loop to help you make sense of what a flagged marker actually means for your specific animal.
Vet-administered panels usually cost more, partly because you’re paying for the office visit and blood draw on top of the lab fee, and partly because these panels are often more clinically oriented — built with input from veterinary genetics researchers and designed to be interpreted alongside your pet’s actual health history. Some general practice vets offer these directly; others will refer you to a specialty lab and handle the sample collection themselves.
There’s also a middle category: kits sold through veterinary channels that you can order without a full office visit, sometimes cheaper than a full vet-administered workup but still more clinically detailed than a general consumer kit. If cost is a major factor, it’s worth asking your vet’s office directly what panels they use and what the total cost looks like once the visit fee is included, rather than just comparing sticker prices between an online kit and a vague idea of “getting it done at the vet.”
One cost-related detail that catches people off guard: the initial test price is sometimes just the beginning. Some services charge a recurring fee for updated reports as their marker database grows, or charge separately if you want a follow-up consultation with a genetic counselor or vet to walk through results. Read the fine print on what you’re actually getting for the price before you buy, especially if the marketing leans heavily on the word “comprehensive.”
What genetic results can and can’t predict about future vet bills
This is probably the most important section to sit with, because it’s where a lot of the marketing overpromises.
Genetic screening can tell you that your pet carries a variant associated with a higher likelihood of developing a particular condition. That’s genuinely useful information in some cases — it can prompt earlier and more targeted monitoring, help your vet interpret ambiguous symptoms faster down the road, and in some breeds, flag drug sensitivities that matter a lot if your pet ever needs anesthesia or certain medications.
What it can’t do is tell you whether your pet will actually get sick, when, how severely, or how much it will cost to manage. Genetics is one input among many. Environment, diet, weight, injury, infection, and plain bad luck all play a role in whether a given dog or cat ends up with an expensive medical problem. A pet can carry a flagged marker and live a long life without ever developing the associated condition. A pet with a clean panel can still end up with cancer, a torn ligament, or a dental disaster that has nothing to do with anything a DNA test would catch.
It’s also worth knowing that a “negative” or clear result on a panel isn’t the same as a guarantee of good health. These panels only test for the markers included in that particular product. A clear result means “we didn’t find the specific things we looked for,” not “your pet has no genetic risk factors of any kind.” New markers get discovered over time too, which is part of why some companies push those recurring update fees.
So if you’re hoping genetic screening will let you calculate a precise future vet bill or decide definitively whether insurance is “worth it” for your particular pet, it won’t get you there. It’s a piece of the picture, not a forecast.
How the timing of genetic testing relative to enrolling in pet insurance can matter for future claims
This is the part that has real financial teeth, and it’s worth slowing down on.
Pet insurance policies exclude pre-existing conditions. That’s standard across the industry and not really up for debate — it’s baked into how the coverage works. A pre-existing condition, broadly speaking, is anything your pet was already showing signs of, or had already been diagnosed with, before your policy took effect (or before the end of any waiting period the policy sets).
Here’s where genetic testing timing gets tricky. If you get a genetic panel done and it comes back flagging a marker for, say, a heart condition or a joint disorder, that result becomes part of your pet’s medical record. If you then apply for insurance after that test, and your pet is later diagnosed with the very condition the test flagged, an insurer reviewing the claim may look at that genetic result as part of the history that suggests the condition wasn’t a bolt out of the blue. Whether that specific scenario leads to a denial depends on the insurer, the specific condition, and how the policy defines pre-existing conditions — this varies enough between companies that it’s not something to guess about in general terms.
This doesn’t mean genetic testing automatically ruins your chances of getting a condition covered. A genetic marker showing increased risk is not the same as an actual diagnosis, and plenty of insurers distinguish between “carries a risk factor” and “has been diagnosed with or shown clinical signs of.” But because insurers do ask about known medical history during application and claims review, and genetic test results can be considered part of that history, it’s a factor worth thinking about rather than ignoring.
The practical takeaway isn’t “never get genetic testing” or “always get insurance first.” It’s that the order of operations can matter, and it’s worth thinking it through deliberately rather than backing into it. If you’re planning to get both a genetic panel and an insurance policy for a new puppy or kitten, it’s worth considering enrolling in insurance first, before you have test results on file, so the policy is underwritten based on your pet’s actual current health status rather than a risk profile. If you already have insurance in place, ask your provider directly how they treat genetic risk markers versus confirmed diagnoses before you order a panel, so you know what you’re walking into rather than finding out after a claim gets scrutinized.
A practical framework for deciding if screening is worth the cost for your particular pet
With all that in mind, here’s a simple way to think through whether genetic screening makes sense for your dog or cat, rather than treating it as an automatic yes or no.
Start with what you’d actually do with the information. If a flagged marker would change how you manage your pet’s care — earlier or more frequent monitoring for a specific issue, a conversation with your vet about anesthesia protocols, adjustments to diet or exercise — then the test has a clear practical use. If you’re mainly curious and wouldn’t change anything either way, the value is more about peace of mind than actionable planning, which is a fine reason to do it, but worth being honest with yourself about.
Consider your pet’s mix and history. If you already know your dog or cat’s breed background well, either because you got them from a source that provided that information or because a breed ID test already gave you a strong read, you may already have a general sense of what conditions tend to run in that background. A vet familiar with that breed mix can often give you a reasonable idea of what to watch for without a full genetic panel, sometimes at no extra cost beyond a normal appointment.
Factor in the total cost against your household budget, not just the sticker price. If money is tight, the cost of a comprehensive panel might be better spent as a cushion toward a vet visit, a dental cleaning, or the first few months of an insurance premium — things with a more immediate, certain return. Genetic testing is informational; it doesn’t pay a vet bill.
Think about sequencing with insurance, as covered above. If you’re getting a new pet and planning to do both, get insurance sorted first, and go into any genetic testing decision with a clear understanding of how your specific insurer treats risk markers versus diagnoses.
Finally, ask your vet what they think, specifically about your pet, before you buy anything. Vets see a lot of these test reports and can tell you, in plain terms, which flagged markers are worth paying attention to for your pet’s actual breed mix and life stage, and which are more of a statistical footnote. That conversation alone, even without ordering a panel, is often the most useful and least expensive step you can take.
None of this means genetic screening is a bad idea. For some owners, especially those with breeds known for specific inherited conditions, it can be a genuinely helpful piece of a long-term care plan. The point is just to go in clear-eyed about what the test can tell you, what it costs in total, and how it fits alongside the insurance decisions you’re already trying to make — rather than treating a DNA kit as a crystal ball for your future vet bills.