If your vet just mentioned that acupuncture might help your dog’s arthritis, or suggested a chiropractic adjustment for your cat’s mobility issues, you’re not alone in wondering whether your pet insurance will actually pay for any of it. These therapies have moved from fringe curiosities to fairly common offerings at general practice and specialty clinics alike, but the insurance industry hasn’t caught up in a consistent way. Some policies cover this care generously. Others barely mention it. A few treat it like it doesn’t exist until you read the fine print and realize it’s specifically excluded. Here’s how to figure out where your policy actually stands.
What counts as ‘alternative’ or ‘complementary’ veterinary care
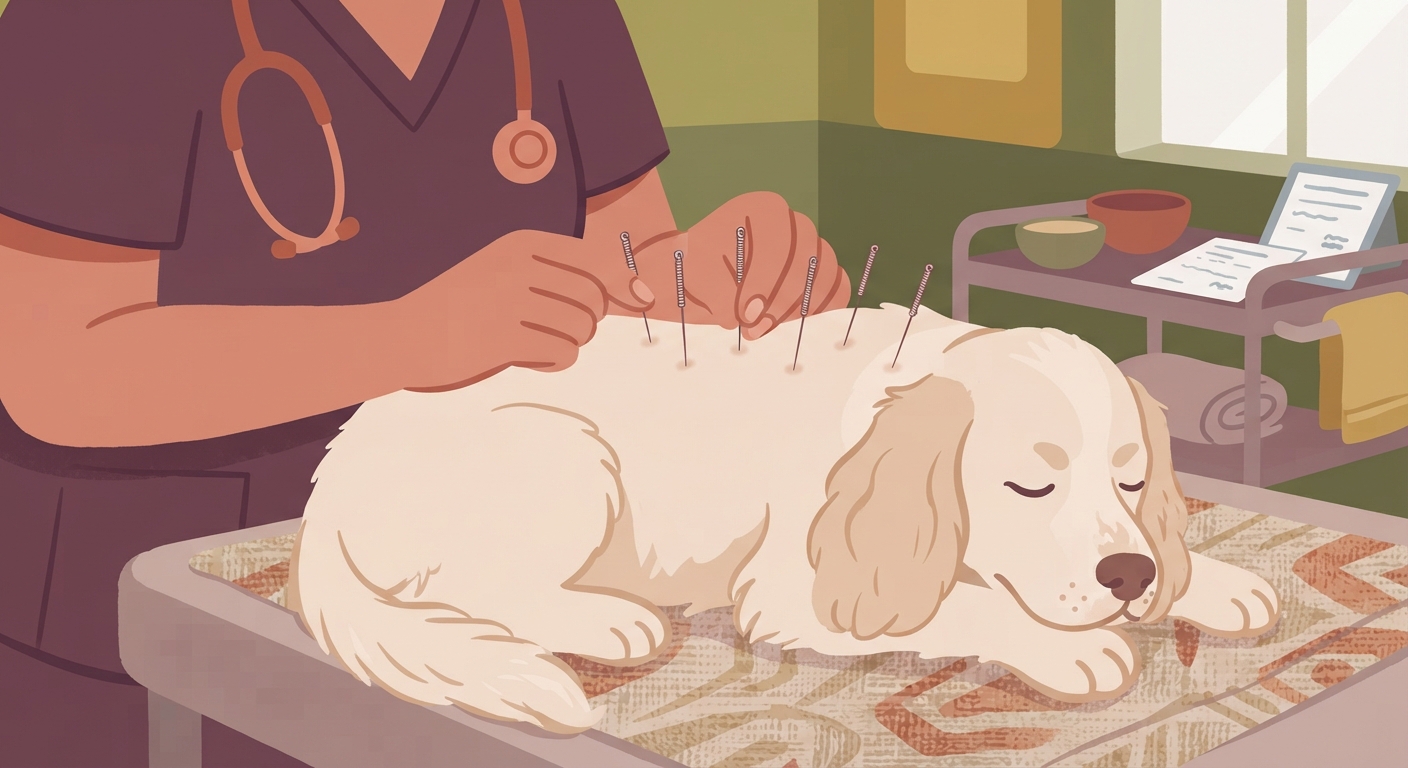
“Alternative” and “complementary” get used almost interchangeably in the pet world, though technically complementary care means treatments used alongside conventional medicine rather than instead of it. In practice, this bucket usually includes acupuncture, chiropractic adjustments, hydrotherapy, therapeutic massage, and sometimes herbal or nutraceutical supplements prescribed by a vet. You might also see cold laser therapy grouped in here, even though many insurers actually classify laser therapy differently since it’s become more mainstream for post-surgical healing and pain management.
What ties these together, from an insurance perspective, is that they’re often performed by veterinarians who’ve pursued additional certification beyond standard veterinary school training. A vet offering acupuncture, for instance, typically has separate credentialing in veterinary acupuncture. That detail matters more than you’d think, because some insurers use “was this performed by a licensed veterinarian” as a gatekeeping question for coverage, while others care more about whether the treatment itself is on their approved list regardless of who administers it.
It’s worth noting that a lot of these therapies are increasingly prescribed for pretty mainstream reasons: post-surgical rehab, chronic pain management in senior pets, mobility support for dogs with hip dysplasia, or recovery from spinal injuries. They’re not just for owners chasing something trendy. That mainstream drift is actually part of why coverage rules are shifting, slowly, in some policies.
How insurers typically classify these treatments in policy language
Pet insurance policies generally sort treatments into a few tiers, and where alternative therapies land depends entirely on the company and the specific plan you bought. The three most common classifications are:
Included under standard accident-and-illness coverage. Some insurers fold acupuncture and chiropractic into their regular coverage for eligible conditions, treating them the same as any other vet-prescribed treatment for a covered illness or injury. If your dog needs acupuncture as part of treating a diagnosed condition, and your policy takes this approach, it gets reimbursed like any other line item on the vet bill, subject to your usual deductible and reimbursement percentage.
Covered only as an optional add-on or rider. Other insurers treat alternative therapies as a separate coverage category you have to purchase on top of your base plan, often bundled with things like behavioral therapy or supplements. If you didn’t specifically add this rider when you bought the policy, claims for acupuncture or chiropractic care will likely be denied even if the base policy sounds comprehensive.
Explicitly excluded, full stop. Some policies simply don’t cover these therapies under any circumstance, regardless of add-ons. This is more common with older or more basic accident-only plans, but it shows up in some accident-and-illness policies too.
The tricky part is that policy marketing language doesn’t always make clear which bucket you’re in. A company’s website might say something like “we cover alternative and holistic therapies,” which sounds reassuring, but the actual policy document might specify that this only applies to certain conditions, only when prescribed by a specialist, or only up to a capped annual amount. The marketing summary and the contract language are not always telling you the same story, so the contract is what matters.
When alternative therapies are covered vs treated as an add-on rider
Generally speaking, coverage tends to hinge on a few variables working together, not just one. The first is whether the therapy is being used to treat a specific diagnosed condition versus being used preventively or for general wellness. A chiropractic adjustment prescribed after your vet diagnoses a specific spinal issue is more likely to be treated as legitimate medical treatment than a standing monthly “tune-up” appointment with no diagnosis attached.
The second variable is whether the treatment is being used as a primary therapy or a complementary one. Insurers seem more comfortable covering acupuncture when it’s paired with conventional treatment for something like post-surgical pain, rather than as a stand-alone approach to managing a chronic condition that could otherwise be treated with medication.
The third, and often most important in practice, is simply whether you added a rider for it. Many companies that don’t include alternative therapies in their base accident-and-illness plan offer what’s sometimes called a wellness add-on or holistic care rider. These riders usually come with their own separate annual cap, meaning even if you have this coverage, you might hit a ceiling of a few hundred dollars a year that doesn’t scale with the base plan’s overall annual limit.
If you’re shopping for a policy specifically because you know your pet might need this kind of care down the road, whether due to breed-related joint issues, age, or an existing diagnosis, it’s worth calling the insurer directly and asking them to point you to the exact section of the policy that addresses acupuncture and chiropractic care by name. Don’t rely on a sales rep’s verbal summary. Ask for the policy document or the certificate of coverage, and read the actual definitions section, since that’s usually where the real boundaries are spelled out.
Common exclusions and documentation requirements
Even when a policy technically covers alternative therapies, insurers tend to build in guardrails that trip people up. Here are the ones that come up most often:
Pre-existing condition exclusions still apply. If your dog’s hip dysplasia was diagnosed before your policy’s effective date, or before a waiting period ended, acupuncture and chiropractic care aimed at that same hip issue will likely be denied on pre-existing condition grounds, even if the therapy itself is nominally covered.
Referral or prescription requirements. Many insurers require that alternative therapy be prescribed by your primary veterinarian, not simply requested by you or performed at a standalone wellness clinic. This usually means keeping a paper trail: a written note or referral in your pet’s medical record showing the vet recommended this specific treatment for a specific diagnosed issue.
Practitioner licensing requirements. Some policies specify that the person performing acupuncture or chiropractic work must be a licensed veterinarian with relevant certification, not a human chiropractor or acupuncturist who also treats animals informally. If you’re taking your pet to someone outside a traditional veterinary practice, check this carefully before you pay out of pocket assuming you’ll get reimbursed later.
Annual or per-condition caps. Even under comprehensive plans, alternative therapies are sometimes subject to a separate sub-limit that’s lower than the policy’s overall annual maximum. You might have a generous overall coverage limit but discover that alternative therapies are capped at a much smaller amount within that.
Session limits. Some policies cap the number of covered sessions per year, per condition, or per policy period. If your vet recommends a course of six or eight acupuncture sessions and your policy only covers four, you’ll want to know that going in rather than after the fact.
Exclusion of specific modalities within the broader category. A policy might cover acupuncture but not herbal supplements, or cover chiropractic but exclude hydrotherapy. “Alternative therapies” as a phrase doesn’t guarantee every modality under that umbrella is treated the same way.
Because of all this, keeping organized records matters more with alternative therapy claims than with a lot of standard vet visits. Save the written treatment plan, the diagnosis notes, and itemized invoices showing exactly what was performed at each visit. If a claim gets denied and you want to understand why, having this paperwork on hand makes it much easier to see whether the denial was about the diagnosis, the practitioner, the cap, or something else entirely.
Typical out-of-pocket costs for acupuncture, chiropractic, and similar care
Costs vary a lot depending on where you live, whether you’re at a general practice or a specialty rehab clinic, and how many sessions your pet needs. A single acupuncture session for a dog or cat is commonly somewhere in the range of a modest specialist visit, though multi-session packages purchased upfront sometimes bring the per-session cost down a bit. Chiropractic adjustments tend to run in a similar range per visit. Hydrotherapy, especially in a dedicated underwater treadmill setup, often costs more per session because of the specialized equipment and staff involved.
What makes these costs add up isn’t usually the price of one visit, it’s the recurring nature of the treatment. Unlike a one-time procedure, acupuncture and chiropractic care for chronic issues like arthritis or degenerative disc disease are often recommended as an ongoing series, sometimes weekly at first and then tapering to monthly maintenance visits. A treatment plan that looks affordable per session can turn into a real recurring line item in your monthly pet budget once you multiply it out over months or years.
This is exactly the kind of situation where knowing your coverage in advance, rather than assuming, makes a real financial difference. If your policy covers these therapies without a restrictive cap, ongoing chronic care can be manageable. If it caps alternative therapy reimbursement at a low annual amount, or excludes it entirely, that recurring cost is one you’ll want to plan for out of pocket, the same way you’d budget for any predictable recurring expense.
Questions to ask your insurer before assuming you’re covered
Before you commit to a treatment plan involving acupuncture, chiropractic care, or another complementary therapy, it’s worth getting specific answers from your insurer rather than relying on general impressions from their website or app. A few questions worth asking directly:
Is this specific therapy included in my base policy, or does it require a separate rider or add-on? If it requires an add-on, can I purchase that now, and is there a waiting period before it takes effect?
Does coverage depend on the treatment being connected to a specific diagnosed condition, or is general/preventive use also covered in any capacity?
Is there an annual dollar cap or session limit specific to alternative therapies, separate from my overall annual coverage limit?
Does the practitioner need to be a licensed veterinarian with specific certification, or are non-veterinary practitioners who treat animals also eligible under my plan?
Will a pre-existing condition exclusion apply if my pet was showing symptoms, or received a diagnosis, before this policy or rider went into effect?
What documentation do you need from my vet at the time of the claim, versus what I should be keeping on file in case of a follow-up request?
Getting these answers in writing, whether through an email from customer service or a screenshot of the relevant policy section, gives you something concrete to refer back to later. It also puts you in a much better